The Headline Number Is Real. The Market Underneath It Is Not.
Managing Partner
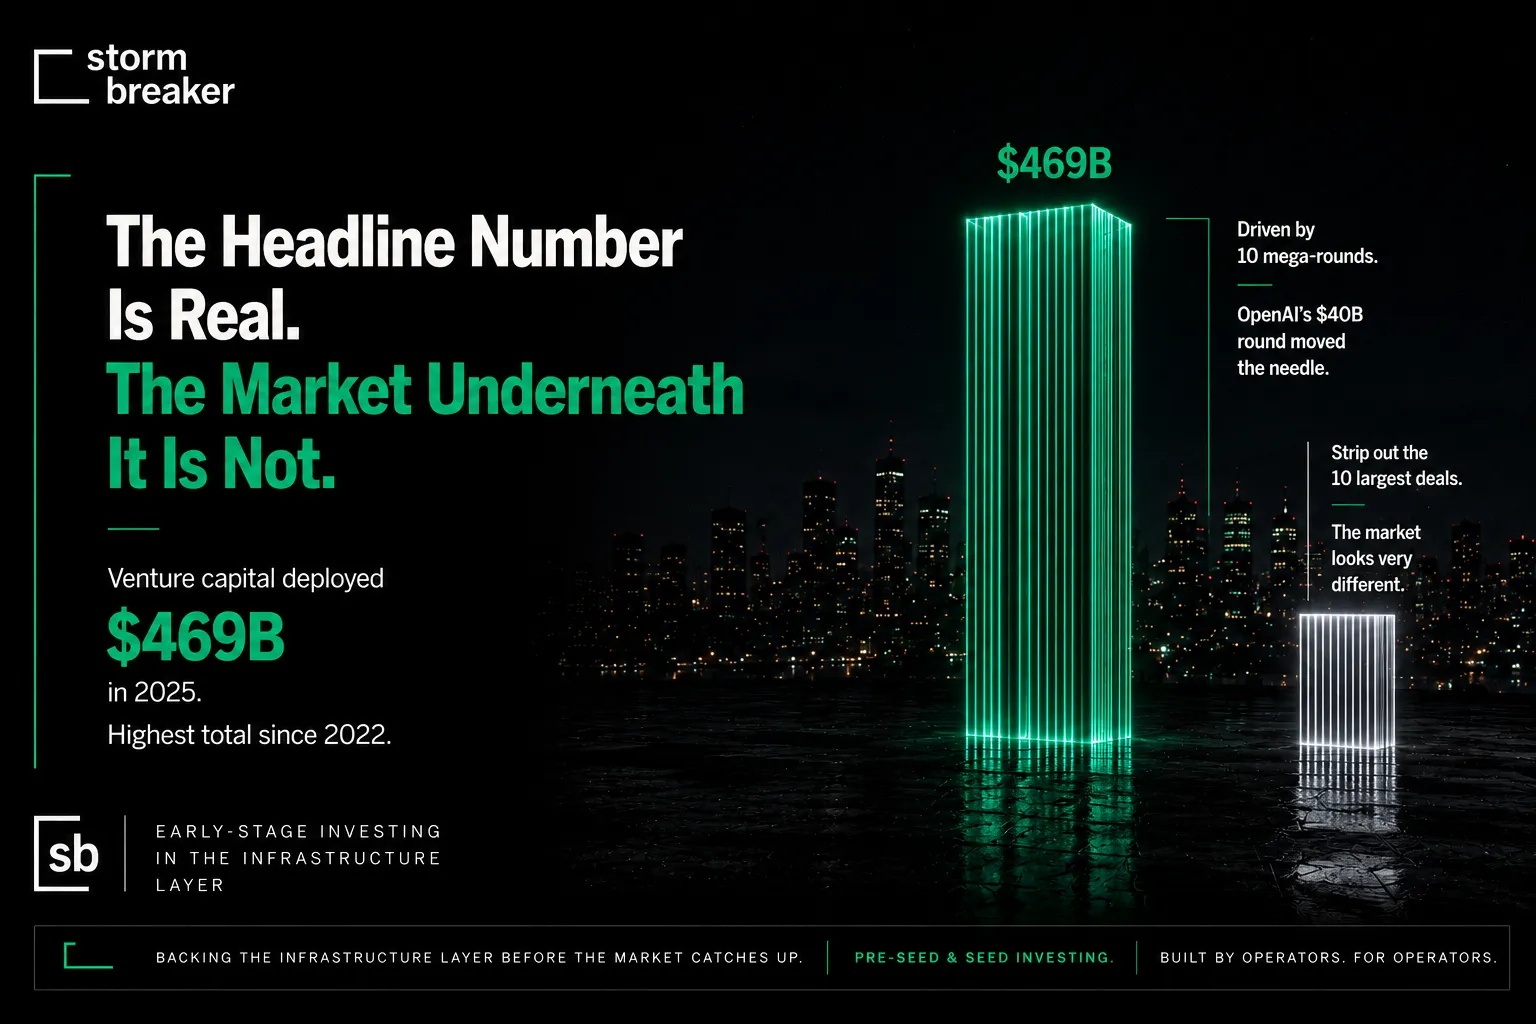
- Venture capital deployed $469 billion last year, but a meaningful share went into a handful of AI mega-rounds. Strip out the ten largest deals and the market most founders are raising into looks very different.
- For edge compute, industrial IoT, and connectivity founders, rounds are taking longer, with more diligence, more proof-of-revenue requirements, and valuations that underweight technical complexity.
- The companies raising well stopped pitching infrastructure and started pitching the outcome it enables. Buyers of the round, like buyers of the product, fund results and inherit architecture.
Venture capital deployed $469 billion last year, the highest total since 2022. If you are a founder reading that number, it sounds like a great time to raise.
For most companies building IoT and edge infrastructure, it is not. The gap between the headline and the experience on the ground is worth understanding, because it explains a lot about how this market actually behaves.
Concentration Distorts the View
The total is real. What it obscures is concentration. A meaningful share of that capital went into a small number of AI mega-rounds. OpenAI's $40 billion round alone moved the annual figure. Strip out the ten largest deals and the picture changes considerably. The average founder is not raising into a $469 billion market. They are raising into whatever is left after the mega-rounds take their share of attention, conviction, and reserves.
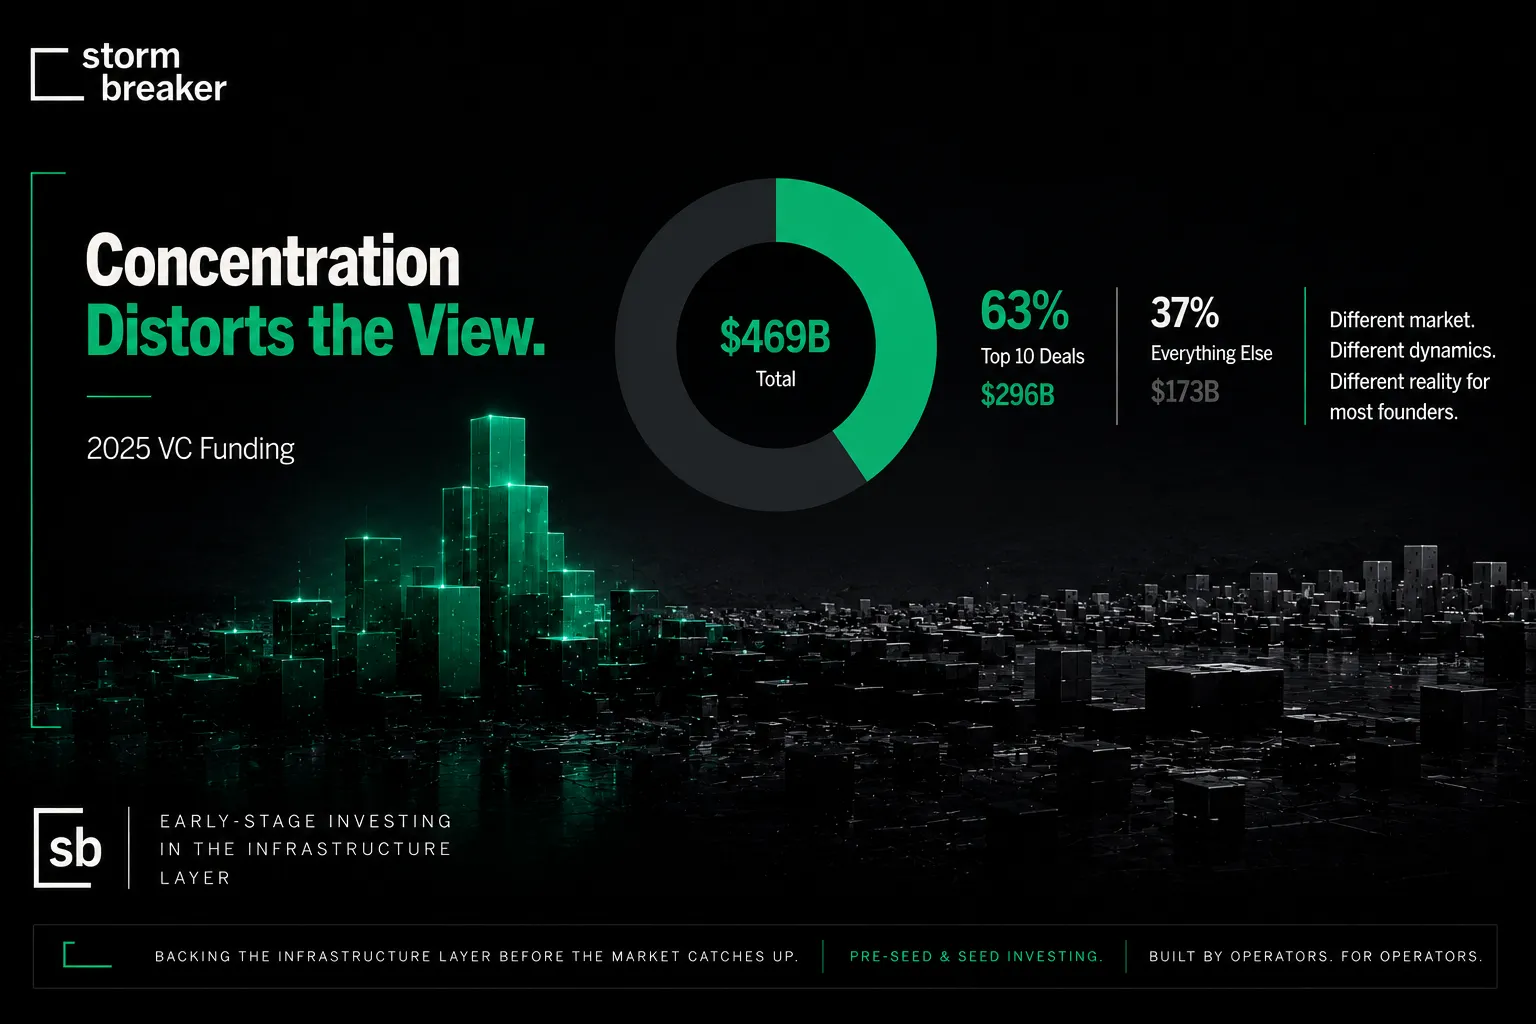
For founders building edge compute infrastructure, industrial IoT platforms, or device-to-cloud connectivity, that remainder behaves very differently than the headline suggests.
Generalist investors are pattern-matching hard toward AI, and if a pitch does not carry an AI-native frame prominently, the meeting gets shorter. Infrastructure rounds are taking longer to close, with more diligence, more proof-of-revenue requirements, and more requests to come back after ten design wins. Strategic investors, the telcos and industrial OEMs and hyperscalers, are more active than they were two years ago, but their timelines are slow and their terms reflect it. Seed and Series A rounds in edge and IoT are getting done, but often at valuations that fail to account for the technical complexity involved or the reality of enterprise sales cycles.
None of this means the category is out of favor with everyone. It means the capital is asking a different question than it asked three years ago.
Sell the Outcome. Win the Round.
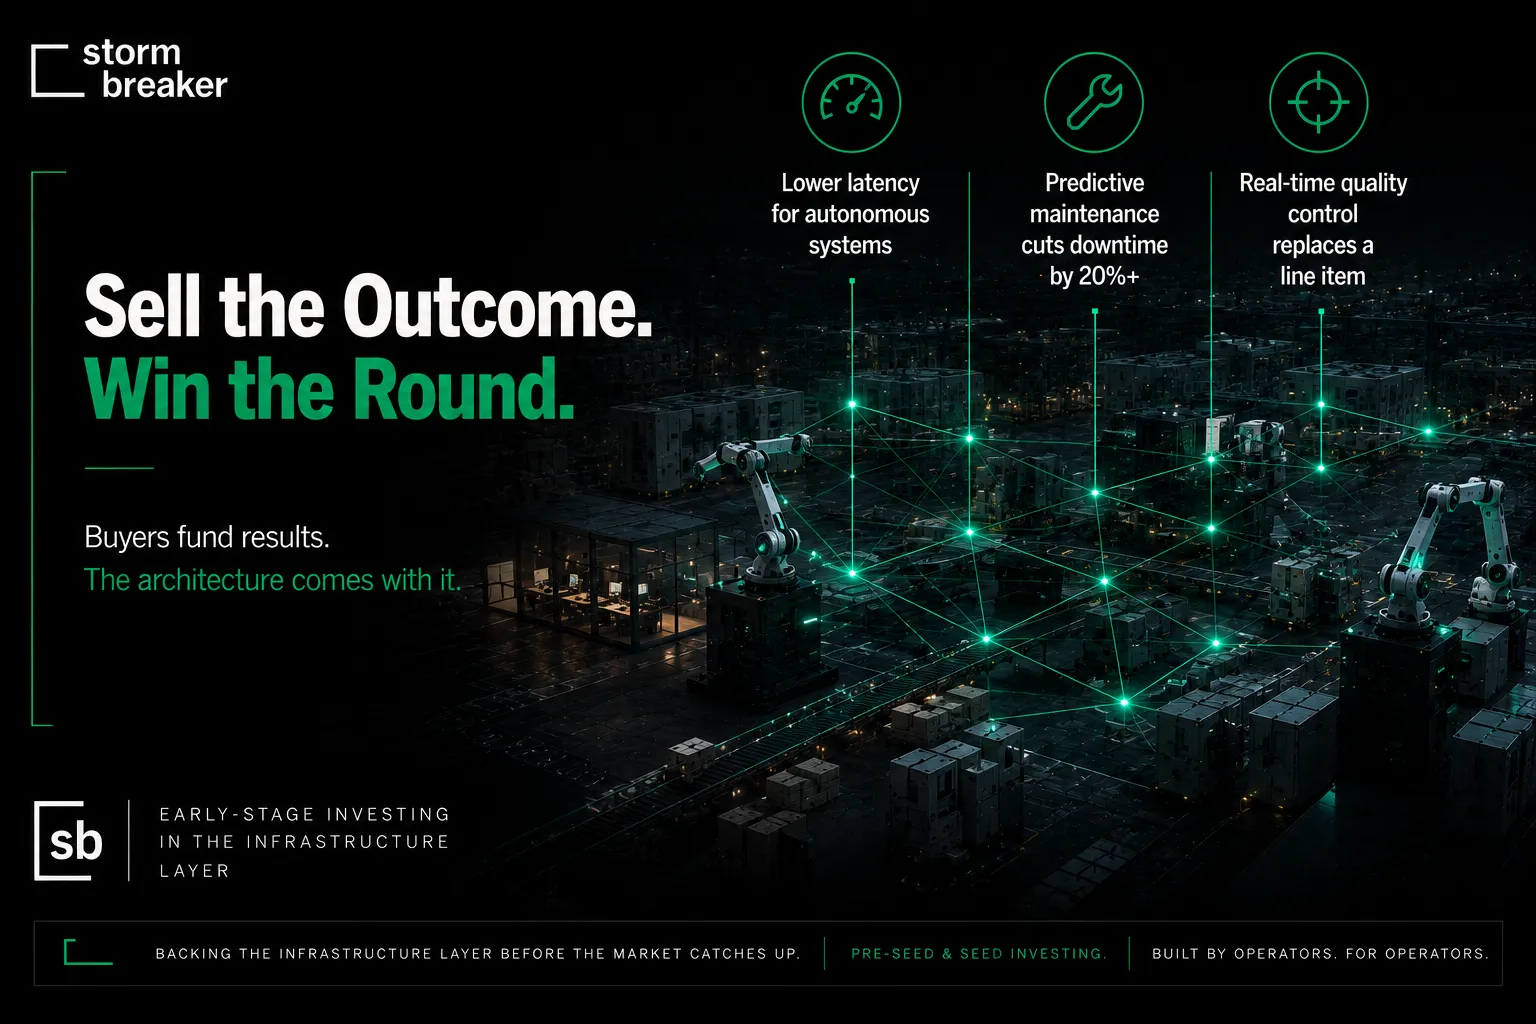
The companies raising well right now tend to share one habit: they stopped pitching infrastructure and started pitching the outcome the infrastructure enables. Lower latency for autonomous systems. Predictive maintenance that cuts downtime by a specific percentage. Real-time quality control that replaces a line item, not a slide. The infrastructure is the means. The outcome is the deal.
The buyer of the round, like the buyer of the product, funds results and inherits architecture.
That is not spin. It is sequencing. The buyer of the round, like the buyer of the product, funds results and inherits architecture.
The capital is out there. It is just not looking for what it was looking for three years ago, and the founders who internalize that early will spend less time in pitch meetings and more time building.
We spend our days with founders at exactly this layer, so we see both sides of the gap: the headline that says the money is everywhere, and the term sheets that say otherwise. If you are building in this space, price the market you are actually in.
Building in the Connected Ecosystem? We find them early. We help them win.
Get in Touch→Perspectives from the connected ecosystem, in your inbox.
Occasional field notes on AI-native connectivity, edge compute, and the infrastructure layer we invest in. No noise.